If you're waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there's a number working behind the scenes that's actually good for you right now. It's called the spread, and once you understand it, you may see today’s rates in a whole new light.
The Pattern That’s Held for 50+ Years
For starters, mortgage rates don't move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.
It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):
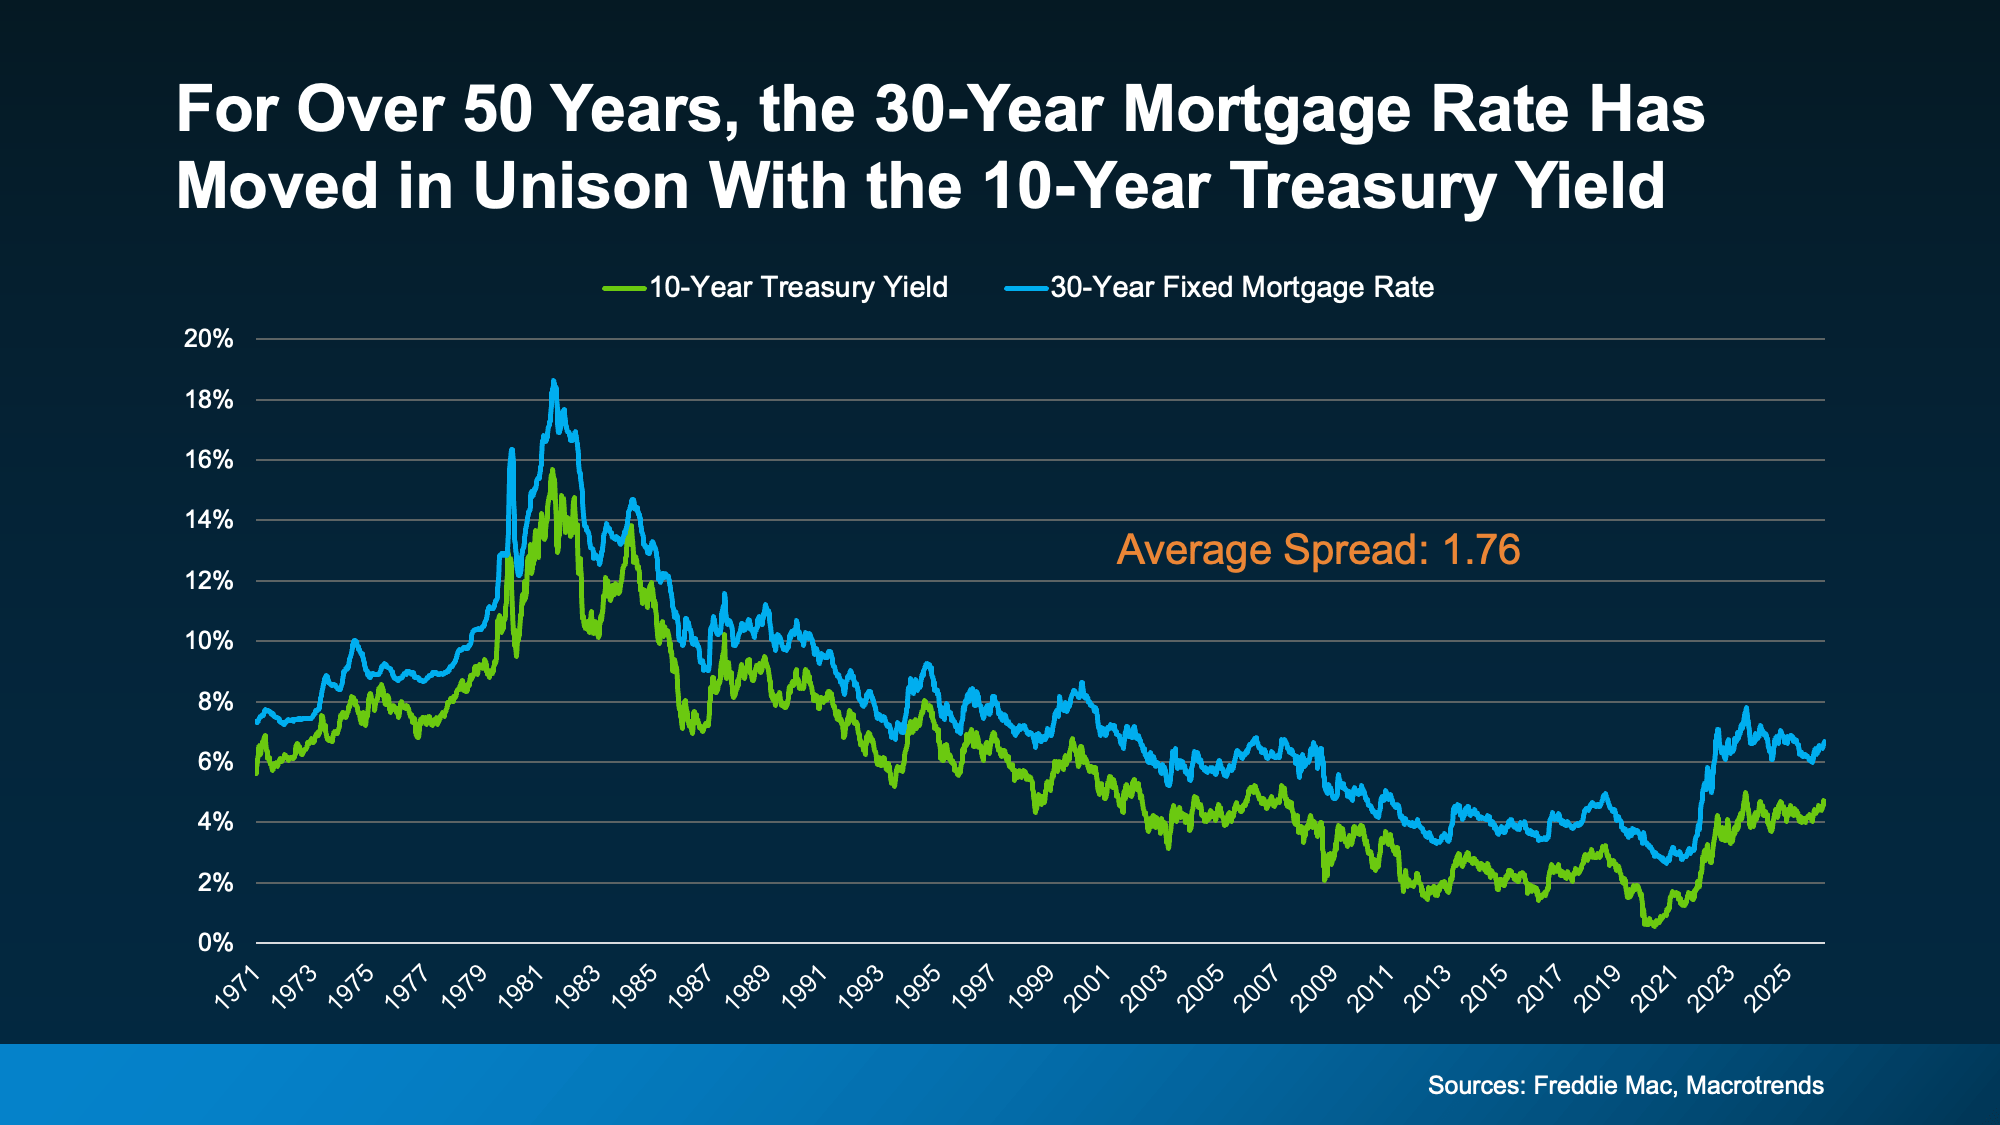
The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.
One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon
If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.
Now here's the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):
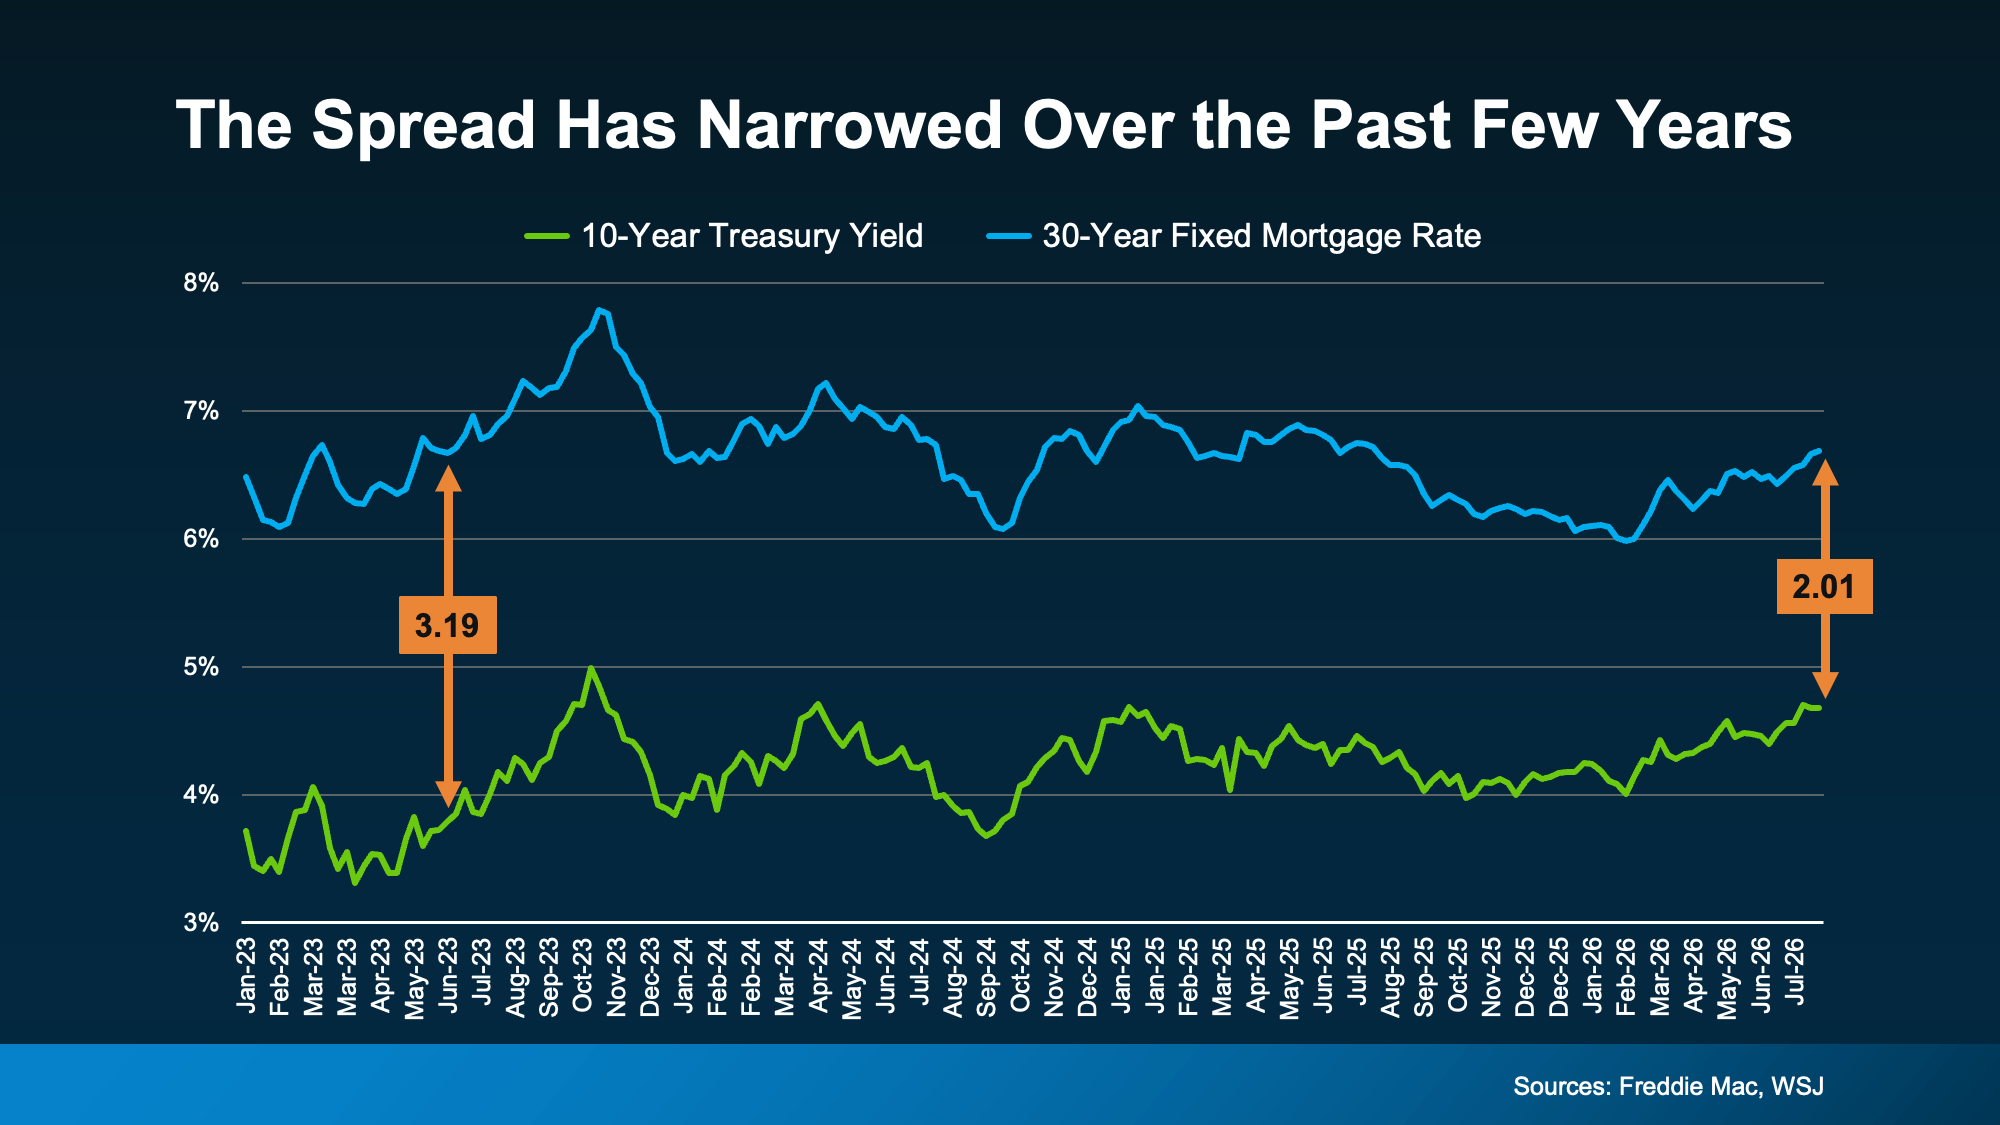
When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.
Why Mortgage Rates Aren’t Higher Right Now
Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today's 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):
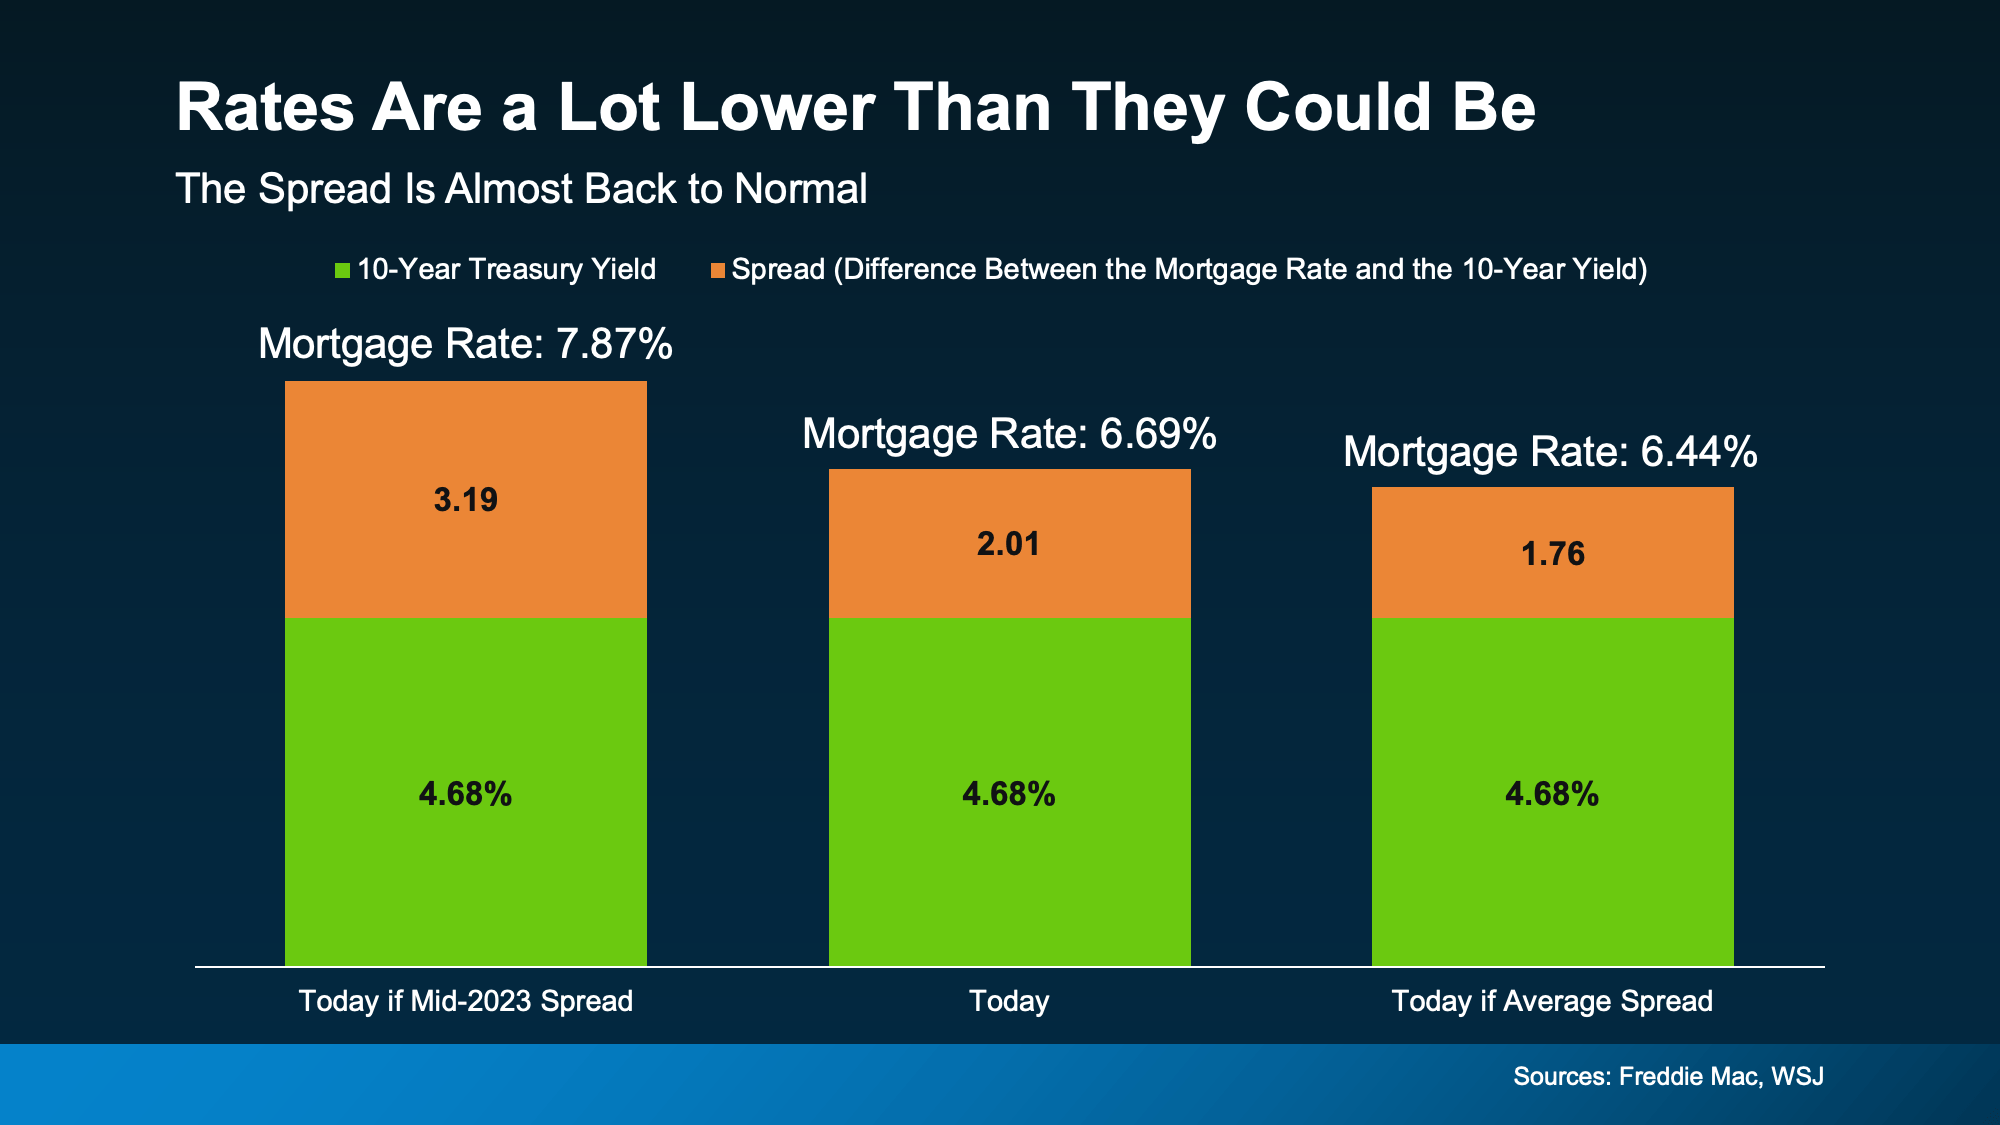
If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.
But now, thanks to the spread narrowing recently, today's rate sits around 6.69%. That’s the middle scenario in that visual. That's a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:
“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”
Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That's only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.
In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.

Why Mortgage Rates May Not Drop Much Lower
Still waiting for mortgage rates to fall? The 10-year Treasury yield and the mortgage “spread” help explain why a major drop may not be coming anytime soon. The spread is the gap between the 10-year Treasury yield and mortgage rates. That gap has narrowed significantly since 2023, which is actually helping keep today’s mortgage rates from being even higher. Before putting your home search on hold hoping for dramatically lower rates, let’s run the numbers and see what makes sense for you.
Still waiting for rates to drop? Two numbers explain why that’s not likely – the ten-year treasury yield and something called “the spread.” They’re also the reason rates aren’t way higher. Let me explain. The spread is the gap between the ten-year treasury yield and mortgage rates. When that gap is wide, rates run higher. Here’s what’s happened lately. Back in twenty-twenty-three, the spread was so wide that if it were still that way today, rates would be pushing almost eight percent. It's narrowed a lot since then, to a spread that’s much closer to normal. So, a rate in the upper sixes, like we’re seeing right now, is actually better than the eight percent it could’ve been had the gap not closed a bit. And since that gap has already shrunk so much, rates probably won’t fall a lot lower anytime soon. So, before you decide to wait and hope for lower rates, reach out to The Kombrink Team and we'll actually run the numbers. Because they’re already better than they could’ve been.
Bottom Line
That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they're better than they could've been. If you want help figuring out what that means for your monthly payment, reach out to a local lender
Posted by The Kombrink Team onEnjoy this blog post? Click here to subscribe for updates
Leave A Comment