How to Buy and Sell a Home at the Same Time in Illinois
What if you could hand over the keys to your old home and unlock your new front door on the exact same afternoon? For many homeowners in Geneva and St. Charles, selling and buying a house at the same time Illinois feels like a high-stakes gamble. You probably worry about the financial strain of two mortgages or the nightmare of moving your family into a hotel. We understand that uncertainty, especially when you're trying to time everything perfectly in a competitive market.
This guide reveals the exact strategies used to manage simultaneous transactions in Kane and DuPage Counties. You will learn how to use your current equity for a new down payment and align your closing dates for a smooth move. We'll explore how the Illinois attorney review period acts as your safety net to ensure a seamless back-to-back closing.
Key Takeaways
- Evaluate the trade-offs between selling first for financial certainty and buying first to ensure you have a new home ready in the Fox Valley.
- Discover how a "Hub-and-Spoke" strategy simplifies selling and buying a house at the same time Illinois by coordinating both transactions through one experienced team.
- Learn to use the unique Illinois attorney review period as a strategic tool to align your closing dates and avoid temporary housing.
- Identify modern financial tools like home equity lines of credit that allow you to tap into your current home's value for a down payment.
Table of Contents
- Deciding Whether to Buy or Sell First in Northern Illinois
- Mastering the Illinois Real Estate Transaction Timeline
- Strategic Tools and Local Resources for a Seamless Move
Deciding Whether to Buy or Sell First in Northern Illinois
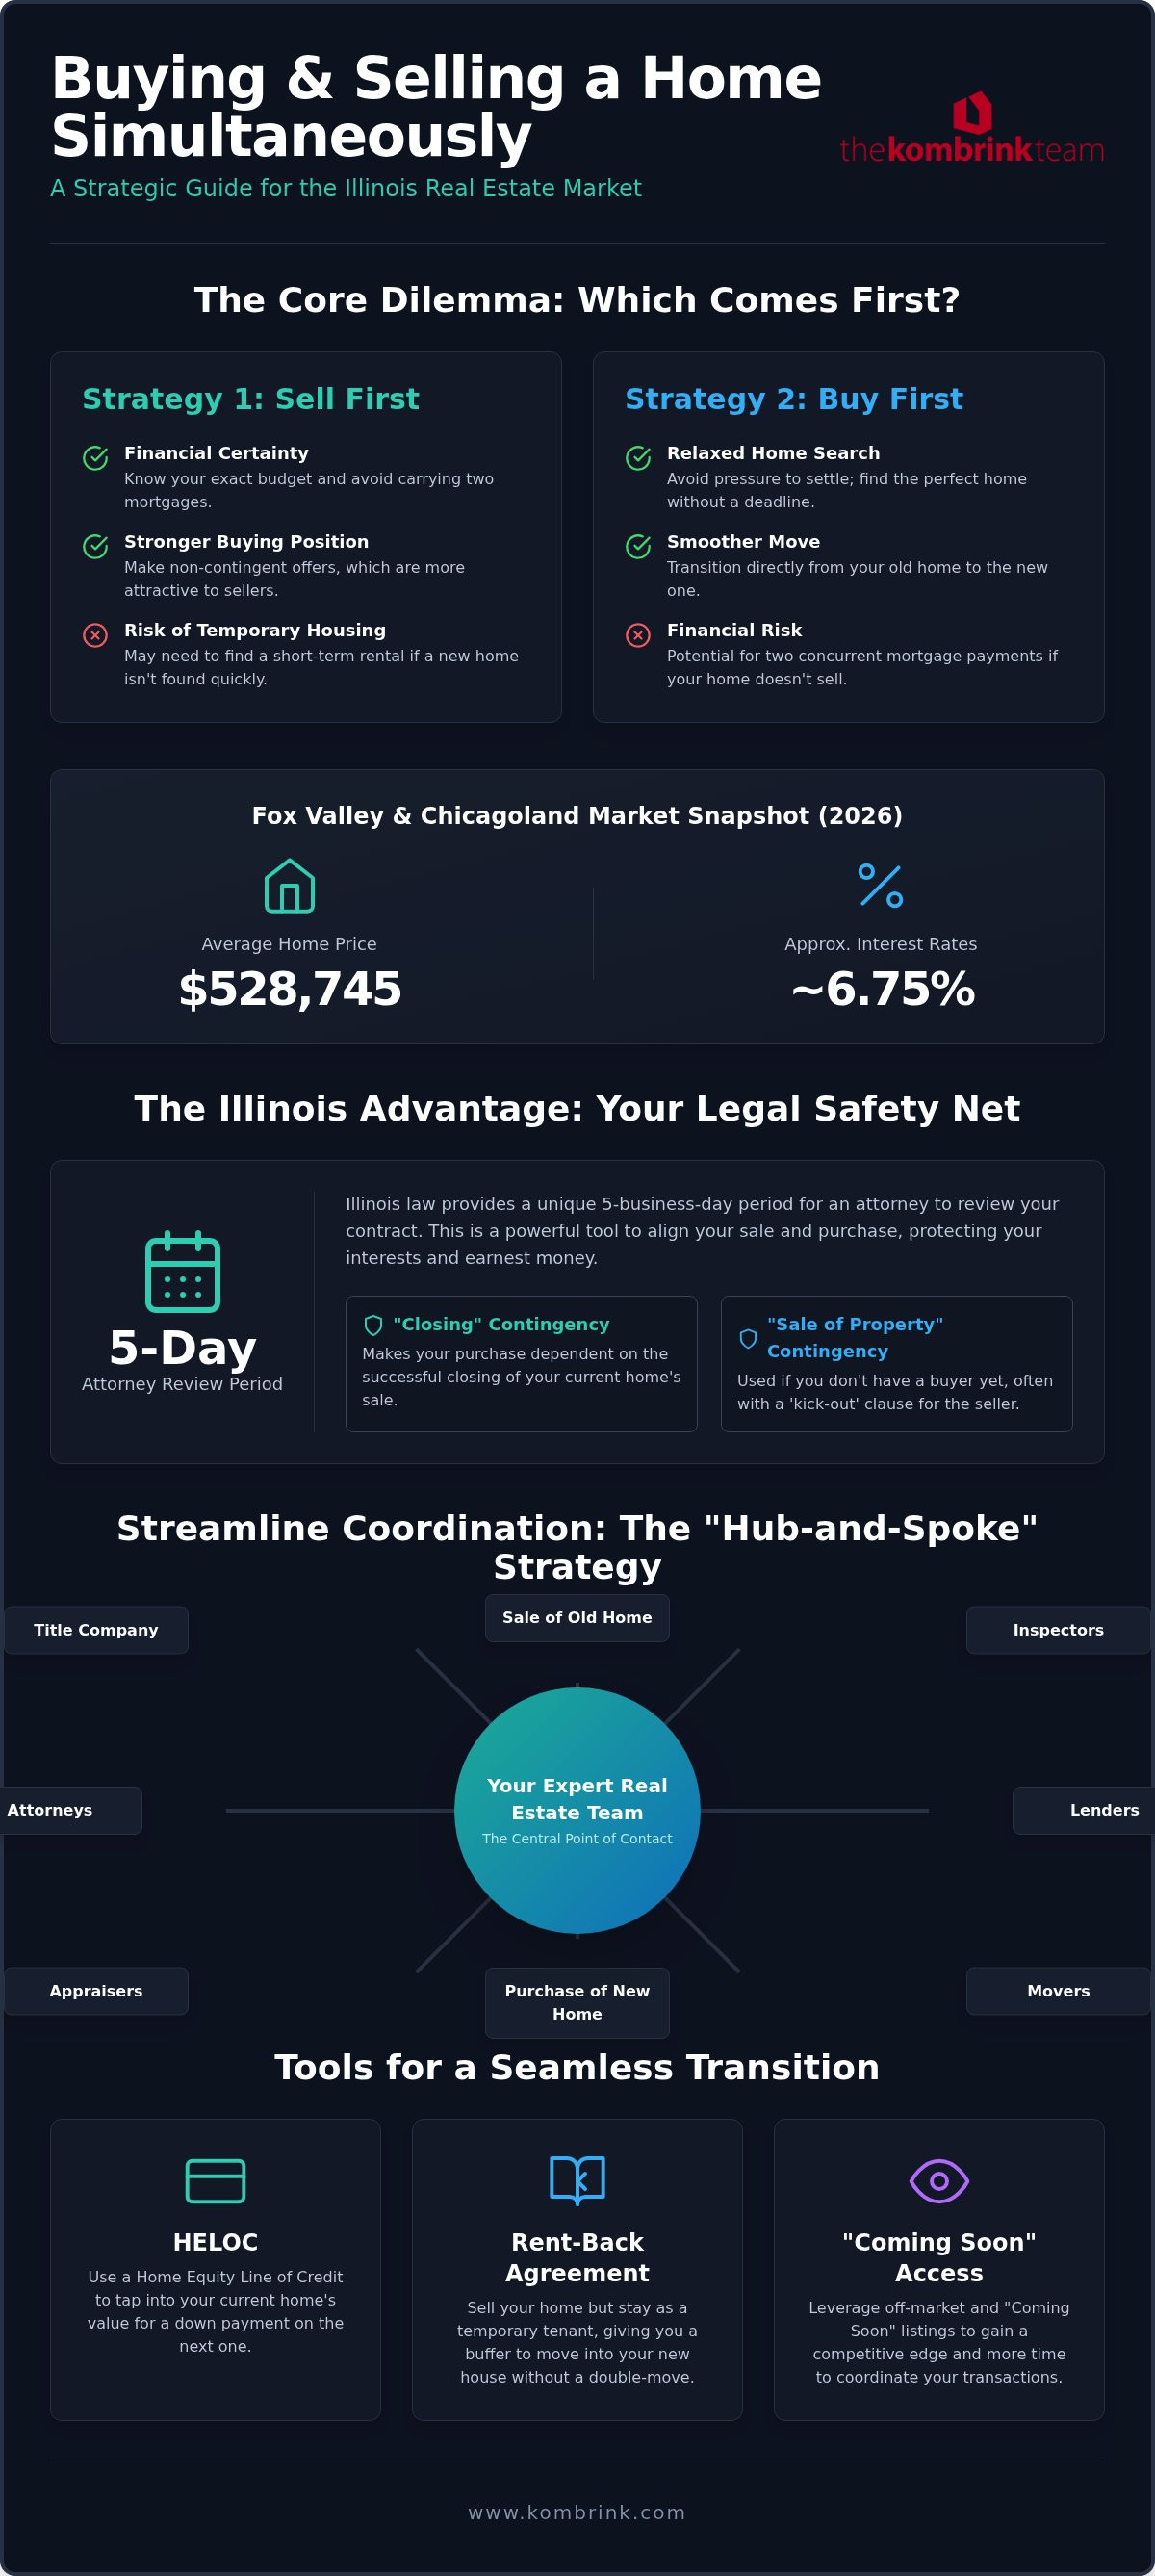
Choosing between buying your next home or selling your current one first is the ultimate chicken-and-egg dilemma. In 2026, the Chicagoland market remains tight, with average home prices sitting around $528,745. Selling first provides immediate financial clarity and prevents the stress of carrying two mortgage payments. However, in high-demand areas like Kane County, it can leave you scrambling for temporary housing if your new home isn't ready.
Buying first offers a more relaxed search experience. You won't feel pressured to settle for a home that doesn't fit your needs just to avoid being homeless. The risk is the potential for concurrent mortgages, which can be a heavy burden with interest rates hovering near 6.75%. Understanding the basics of a real estate contract is vital here, as it dictates how and when you can exit an agreement if your current home doesn't sell as planned. Successfully selling and buying a house at the same time Illinois requires a strategy tailored to these specific financial risks.
Evaluating Your Equity and Local Market Conditions
Your strategy should start with a professional home valuation report to determine your actual borrowing power. Market conditions vary wildly across the suburbs. We see high competition and low inventory in established hubs like Naperville, where sellers often hold more leverage in negotiations. Conversely, smaller markets like Elburn might offer a bit more breathing room but require a different approach to timing. Knowing whether you're in a seller's market dictates your leverage when asking for a home sale contingency.
Mastering the Illinois Real Estate Transaction Timeline
Coordinating two deals requires a "Hub-and-Spoke" model where your real estate team acts as the central point of contact. This ensures that inspection deadlines on your sale don't conflict with appraisal dates on your purchase. Managing two sets of paperwork is much easier when your professionals communicate in real-time. This coordination is essential for selling and buying a house at the same time Illinois, especially when trying to schedule a back-to-back closing at a single title company.
We often see move-up buyers struggle with the logistics of moving their belongings between the two properties. A well-coordinated timeline allows you to sign your sale documents in the morning and your purchase documents in the early afternoon. This sequence ensures the proceeds from your sale are available for the new down payment immediately. It eliminates the need for temporary storage or staying in a hotel while you wait for funds to clear.
Attorney Review When Selling and Buying a House at the Same Time Illinois
In Illinois, the standard contract includes a five-day attorney review period. This is a powerful safety net rooted in Illinois property laws that allows your legal counsel to modify terms for your protection. Unlike states where agents handle all modifications, the Illinois process relies on legal experts to tailor contingencies. During this time, we can structure a "Closing" contingency, which protects your earnest money if your current home sale fails to close.
If you haven't found a buyer yet, a "Sale of Property" contingency is used, though it often includes a 72-hour kick-out clause. This clause allows the seller to keep their home on the market and gives you three days to firm up your offer if they receive another bid. It's a delicate balance of protecting your interests while you transition. If you have questions about how these timelines apply to your specific move, feel free to reach out to our team for a quick chat.
Strategic Tools and Local Resources for a Seamless Move
How do you pull this off without the logistical headache? One of the most effective ways is using a Home Equity Line of Credit (HELOC) on your current residence. This strategy allows you to tap into your existing equity for a down payment before your sale is finalized. Another powerful local tool we often suggest is the "Rent-Back" agreement. This allows you to sell your home but remain as a tenant for a short period, providing the necessary buffer to move into your new home without a double move.
We also recommend leveraging "Coming Soon" listings to gain a competitive edge. In high-demand areas like Geneva or Batavia, the best homes often have interest before they hit the general market. This insider access is a vital component when selling and buying a house at the same time Illinois, as it gives you more time to coordinate your sale without feeling rushed by the general public market.
Financing Your Move Without Two Mortgage Payments
Success depends on working with local lenders who specialize in simultaneous Illinois closings. These experts can help you structure your financing so you aren't carrying the weight of two full mortgage payments. Our home buyer services connect you with vetted professionals who understand the nuances of the Fox Valley market. To understand the licensing standards and expertise required for complex mortgage scenarios, read more. They can guide you through bridge loans or specialized products designed for move-up buyers.
It's also critical to prepare for closing costs on both sides of the transaction. Remember that the Illinois state transfer tax increases to $0.75 per $500 of the sale price on July 1, 2026. Budgeting for these fees early ensures a smooth transition to your new front door. Having a clear financial picture prevents last-minute stress and keeps your focus on the excitement of your new home.
Start Your Next Chapter with Confidence
Successfully selling and buying a house at the same time Illinois doesn't have to be a stressful gamble. By leveraging the unique Illinois attorney review period and strategic tools like rent-back agreements, you can transition between homes with a single move. The key is coordinating every detail through a team that understands the specific nuances of the Kane and DuPage County markets.
With 30+ years of local experience and over 4,290 homes sold, we've helped thousands of families manage these complex double-closings. As the team ranked #1 in Kane County, we're proud to be the steady hand that protects your equity and your timeline. You deserve a seamless experience that focuses on your future rather than the logistics of the move.
Ready to get started? Schedule your free simultaneous move consultation with The Kombrink Team today. We look forward to guiding you home.
Frequently Asked Questions
Can I close on my old house and new house on the same day in Illinois?
Yes, you can close on both properties on the same day, which is known as a back-to-back closing. We frequently see sellers complete their sale in the morning and use those funds to buy their next home in the afternoon. This requires precise coordination between your lender and attorney to ensure funds transfer correctly through the title company without delays.
What is a home sale contingency and how does it work in Kane County?
A home sale contingency makes your purchase offer dependent on the successful sale of your current residence. In Kane County, sellers often include a 72-hour kick-out clause with this contingency. This allows the seller to keep their home on the market and gives you a three-day window to firm up your offer if they receive a better bid from another buyer.
Is it better to buy or sell first in the current 2026 market?
In the current 2026 market, the best choice depends on your tolerance for risk and your financial situation. Selling first provides the most financial certainty, as you'll know exactly how much equity you have for your next down payment. However, buying first is popular for move-up buyers who want to secure a specific home in low-inventory areas like Geneva before selling their own.
How does the Illinois attorney review period protect me during a double move?
The five-day attorney review period allows your legal counsel to add protective language that national contracts often lack. When selling and buying a house at the same time Illinois, your attorney can synchronize the two contracts so you aren't forced to close on a new home if your current sale fails. This legal window is your primary defense against the financial strain of unexpected double ownership.
Disclaimer
This article is provided for general informational purposes only and is not intended as legal, tax, financial, or mortgage advice. Real estate laws, market conditions, rates, and individual circumstances can change. Consult the appropriate licensed professional regarding your specific situation.
Enjoy this blog post? Click here to subscribe for updates
Leave A Comment